

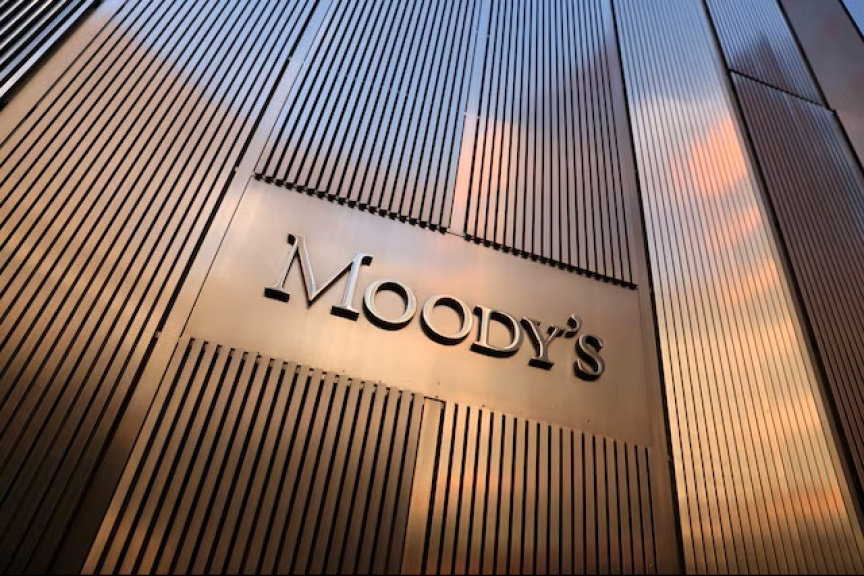
Signage is seen outside the Moody's Corporation headquarters in Manhattan, New York, United States, November 12, 2021. (Photo/Reuters)
Moody’s has declared that Maldives’ sovereign credit rating has been lifted to Caa1, a rise wrought from the government’s ability to settle its towering external debts whilst ushering in strong measures to capture foreign-currency inflows.
The agency said on Thursday that these efforts have substantially softened the risk of future default, allowing the outlook to remain “stable”.
In its latest reading of the nation’s economic footing, Moody’s said the upgrade was steered by more resilient foreign-exchange reserves, strengthened Sovereign Development Fund (SDF) balances, and continued bilateral financing. The agency noted that the government has already discharged the USD 500 million sukuk due in April. Two USD 50 million Treasury bills and a USD 400 million currency-swap facility were likewise repaid, whilst the USD 100 million owed to the Abu Dhabi Fund has now been pushed to 2031.
Moody’s Ratings has upgraded the Maldives’ Sovereign Credit Rating from “Caa2” to “Caa1” with a stable outlook. The agency cited the successful repayment and refinancing of significant debt obligations maturing this year, along with improved external buffers, resulting from the Government’s coordinated efforts as the rationale for this rating upgrade. Press Release: https://t.co/bienROponh
— Ministry of Finance and Public Enterprises (@MoFmv) October 8, 2026
Moody’s said these repayments have pared down external debt from USD 2.8 billion (35 percent of GDP) at end-2025 to USD 2.4 billion (30 percent of GDP) by the second quarter of 2026. With USD 411 million left to settle in the final quarter of this year, next year’s burden falls to USD 428 million, easing the sovereign’s near-term repayment strain.
The agency attributed much of this progress to the government’s vigorous foreign-exchange measures introduced through late-2024 and 2025. Regulations compelling tourism-earned dollars to be deposited and converted through domestic banks, alongside the levying of tourism-related taxes in foreign currency, have kindled a stronger capture of inflows. As a result, reserves had swelled to USD 1.3 billion, and the SDF brimmed at USD 320 million before major repayments were made.
Despite the upgrade, Moody’s reminded that Caa1 remains a low rating, and the economy must tread carefully amidst rising oil and transport costs. With the fiscal deficit expected to widen to 8.0 percent, 8.5 percent of GDP in 2026, the agency urged vigilance in maintaining fiscal discipline.